Guide · 07/10/2026 · 6 min read
Regular Buying vs One-Off Purchase: How to Accumulate Gold
Anyone buying gold runs into the same question sooner or later: should you put the whole planned amount into a single purchase, or build a holding gradually with smaller instalments over time? Both approaches have their own logic, their own costs and their own practical snags. Below we set them side by side so you can judge which one fits your situation.
What separates regular buying from a one-off purchase
A one-off purchase means the investor commits the full planned amount in a single transaction — one one-ounce coin, say, or a 100-gram bar. Regular buying (often called dollar-cost averaging) means splitting that same amount into instalments bought on a fixed rhythm: every month, every quarter, or whenever the savings account has built up enough.
The real difference is when you take on price risk. A one-off purchase locks in a single entry price. Regular buying gives you several entry prices whose average lands somewhere in the middle — some instalments bought high, some bought low.
Why gold’s price swings matter here
Gold does not move in a straight line. According to World Gold Council data, gold’s annualised volatility has mostly stayed between 10% and 18% since 1971, though in 2026 it climbed into the top fifth of that data series. The same analysis notes that gold’s volatility tends to revert to the mean — historically, the “half-life” of a volatility shock has been around 1.6 months, much like equities.
Over long horizons the direction has been upward: the World Gold Council’s long-run review puts the rise in the US dollar gold price at roughly 9% a year on average since 1971. That is a historical average, not a promise — any single year can be sharply up or sharply down.
In practice this means two things. First, over short horizons, picking the “right” moment to enter is largely luck. Second, the bigger a single transaction is relative to your total holding, the more the outcome hangs on that one day.
Where regular buying is strong
It spreads price risk across time. Buy every month and no single peak or trough dictates your average cost. That is no guarantee of a better result, but it does trim the extreme outcomes in both directions.
A lower entry threshold. If a full ounce in one go is out of reach, you can start with smaller units. For a sense of scale: on 6 October 2026, Kitco’s market report had spot gold trading near $4,165 an ounce and silver near $61.26 an ounce. One ounce of gold is a far larger single ticket than, say, a 10-gram bar or a fractional-ounce coin.
The power of habit. Regular buying is a discipline: the amount is decided in advance, and the moment of purchase does not depend on whether the news flow happens to be frightening or exhilarating.
Where regular buying is weak
Premiums are higher on small units. The retail price of physical gold is the spot price plus a premium covering minting, logistics and handling. As a percentage, that premium is generally larger on smaller units. Ten 1/10-ounce coins typically cost more in total than a single full ounce of the same purity.
More transactions, more paperwork. Every purchase means its own invoice, its own acquisition cost and its own line in your records.
In a rising market you leave some of the move on the table. If the price climbs steadily through your buying period, the instalment buyer’s average cost ends up higher than that of someone who bought everything at the start. In the opposite scenario, the opposite holds.
The one-off purchase: strengths and weaknesses
Cost structure argues for the one-off purchase: a single larger unit is usually cheaper per gram, there are fewer transaction and handling costs, and the record-keeping is simple — one invoice, one acquisition cost. If the money is already available and the plan is to hold the metal for a long time, this is a clear and inexpensive route.
The flip side: the price for the entire amount is fixed on one day. If that day turns out, in hindsight, to have been a local peak, you simply live with it. Psychologically, many people find that harder than a staged entry.
Choosing in practice: units and weights
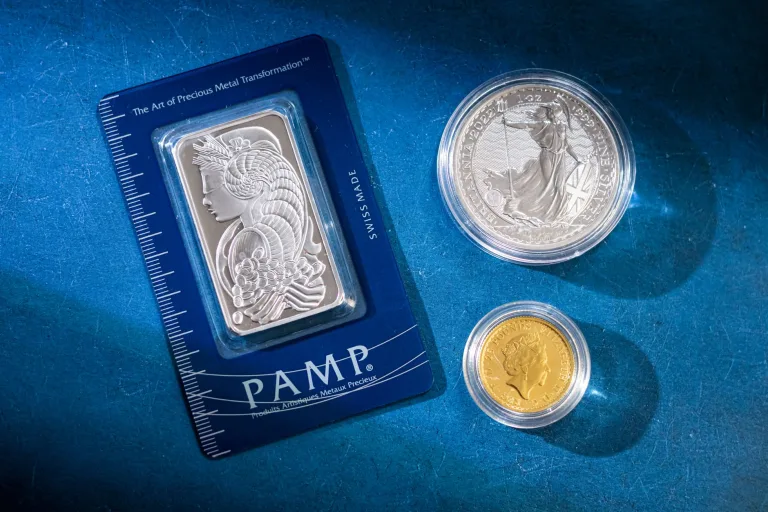
If the plan is to accumulate gradually, the choice is not only “how often” but also “in what form”. Fractional ounces and smaller units suit a smaller step — Austrian Philharmonic gold coins and Canadian Maple Leaf gold coins, for instance, come in several weights, which lets you adjust the size of the step over time. Anyone who prefers bars will find the same logic in the Argor-Heraeus gold bar range.
Some investors use silver to lower the entry threshold, since the price per unit is several times smaller — one-ounce silver coins, for example. There is an important tax difference here, though: in Estonia the supply of investment gold is exempt from VAT (under § 16 of the Value Added Tax Act), while silver gets no such relief and its retail price includes VAT.
Tax records: every purchase is its own acquisition cost
One practical consequence of regular buying is documentation. A private person declares the gain from selling gold in table 6.3 of the income tax return, following the Estonian Tax and Customs Board’s guidance, and only profitable sales have to be declared, because losses on gold sales cannot be offset. That means the acquisition cost deducted from the sale price has to be provable — keep the invoice for every purchase.
More purchases, more lines. A simple table with the date, quantity, unit price, amount paid and invoice reference keeps things manageable even once dozens of purchases have piled up over the years.
A practical framework
If you want to set up regular buying, three decisions need to be made up front: the amount (how much per step), the interval (how often) and the unit (what weight of metal you buy). When the savings step is small, it is worth asking whether buying less often in larger units would keep the premium per unit lower. Some buyers let the money accumulate in an account and then make one solid transaction per quarter — a compromise between spreading price risk and controlling cost.
Which approach is better depends on whether the money already exists or arrives gradually, how long your horizon is, and how well you tolerate price swings. If the full amount is already on hand and the aim is long-term holding, the one-off purchase is more cost-efficient. If the money arrives from a salary month by month, regular buying is effectively the only route available — and then the question is really how big one step should be.
Frequently asked questions
Does regular buying guarantee a better result? No. In falling or sideways markets the average cost comes out lower; in a steadily rising market it comes out higher. Regular buying reduces your dependence on a single day, not price risk itself.
How small a purchase still makes sense? The premium sets the floor. Once the percentage premium on the smallest available unit stops being reasonable for you, lengthening the interval — buying less often, in a larger unit — is generally more cost-efficient.
Do I have to keep the invoice for every purchase? Yes, and it is strongly advisable. Acquisition cost can only be deducted if it can be proven.
Can I combine the two? Yes. One common pattern is to make a single larger base purchase at the outset and then top it up with smaller regular buys.
This article is for informational purposes only and does not constitute investment advice or a solicitation to buy or sell precious metals. Precious metal prices fluctuate. Before making any investment decision, consider your own circumstances and consult a specialist if necessary.
Goldman & Sons editorial team